 Iranco Magazine Team
Production ecology, cocoa and CBS inputs, holding benchmarks, shelf channels and R&D trends in Iran’s industrial confectionery
Market report · Chocolate & biscuits · FMCG value chain
The Sweet Pulse of Food Economics: Competitive Anatomy, Value Chain and Brand Battles in Iran’s Chocolate & Biscuit Industry
Iran’s confectionery, chocolate and cereal-products industry is one of the Middle East’s most complex and developed FMCG segments. This report examines production ecology, input politics, player benchmarks, trade channels and process innovation.
1. Ecology and geopolitical advantage of Iran’s confectionery industry
Built largely on genuine private capital rather than traditional state rents, the industry links international supply chains with domestic engineering. Spatial development rests on two hubs with distinct economic logic.
Hub geography: Tabriz cluster vs Alborz–Tehran
East Azerbaijan and greater Tabriz form the historic capital of the trade. Official figures put more than 50% of national volume and 55–60% of confectionery export earnings in this region. Intra-cluster synergies in parks such as Shahid Salimi unlock economies of scale and horizontal clustering — machine building, moulds, rotogravure/flexo print, cartons, egg and glucose processing beside the lines. Proximity to Caucasus and Turkey corridors and Bazargan terminal shortens CIS/Europe access and border logistics. Dadash Baradar (Aidin), Shirin Asal, Shoniz, Anata and Ghaflankuh exemplify the ecosystem.
Alborz and Tehran (Special and Old Karaj roads) are the consumption-facing processing hub. Farmand (Parand Chocolate), Minoo and Baraka sit here. The advantage is adjacency to an 18-million-plus capital market and national distribution — higher land and wage costs, but lower inventory float into hypermarkets.
Export performance and idle capacity
Exports peaked near USD 1 billion in 2016–2017; banking friction, structural inflation and FX repatriation rules later compressed trade to about USD 350–400 million. Nameplate machinery capacity is about 3.4 million tonnes/year versus roughly 2 million tonnes of actual output — nearly 50% idle capacity, mainly from working-capital limits, scarce competitively priced imports and export friction.
Iranian products reach 60+ countries. Iraq takes about 45% of cocoa confectionery exports, followed by Afghanistan, Pakistan, Azerbaijan, Turkmenistan and the Gulf. With smoother finance and stable rules, analysts see a path to USD 1.5–2 billion annual exports.
Catalogue diversity matrix
- Cereal products & biscuits: hard biscuits (petit beurre, digestive), rotary-moulded softs, fermented crackers, filled cookies and wholegrain diet lines.
- Cake & wafer: sponge, cupcakes, Swiss rolls, flat and cone wafers — plain, cream-filled and compound-coated.
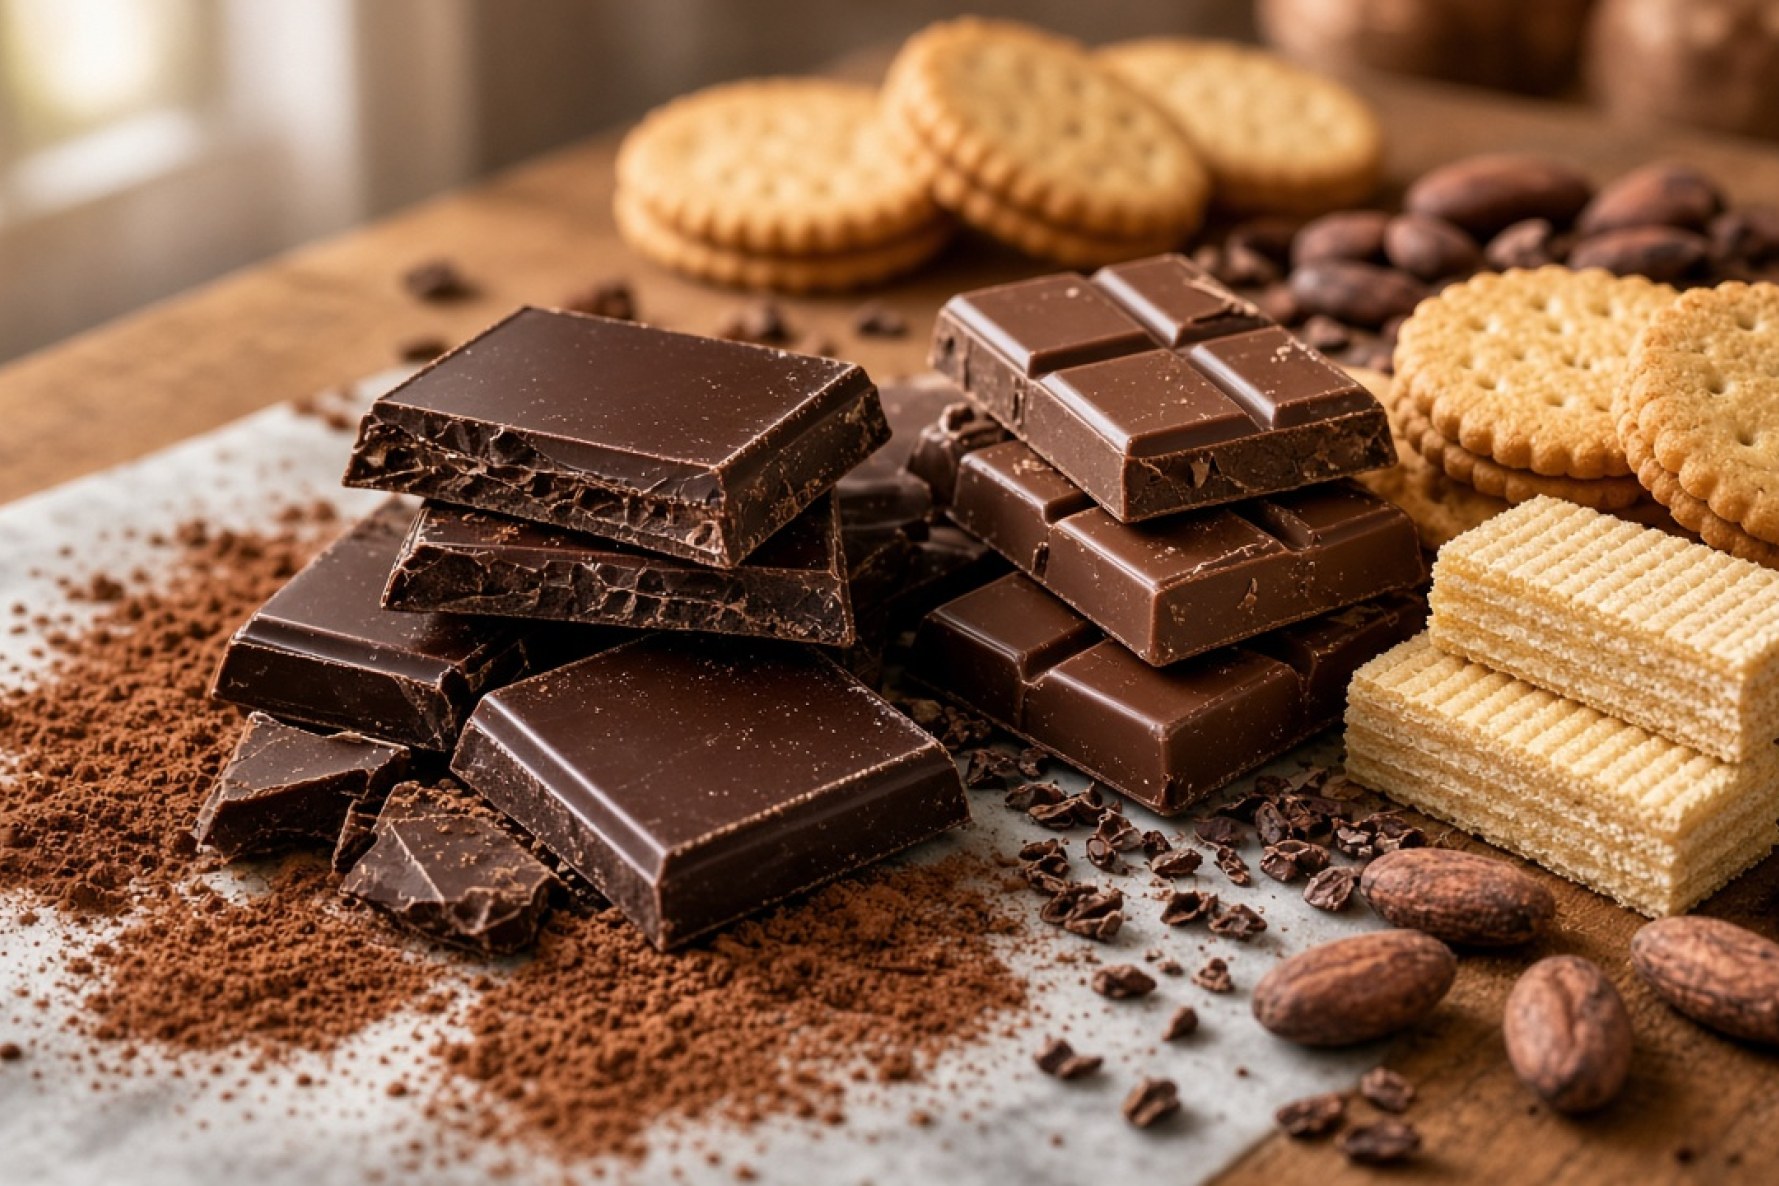
- Cocoa & chocolate: dark-to-milk tablets, pralines, truffles, countlines, hospitality assortments and gift hardboxes.
- Sugar confectionery: butter/milk toffees, filled chewies, caramel, hard-boiled candy, gelatin/pectin jellies and sugar-free dragee gum.
2. Supply-chain bottlenecks: commodities and base inputs
Margin resilience hinges on commodity volatility and food chemistry. Value flows at the junction of imported international raw materials and domestic cereal processing.
Natural vs alkalized cocoa powder
Iran cannot grow cocoa; beans and derivatives arrive mainly from West Africa (Côte d’Ivoire, Ghana — aromatic Forastero) and Southeast Asia (Indonesia, Malaysia).
| Type | pH & colour | Sensory profile | Primary use |
|---|---|---|---|
| Natural | 5.0–6.0; lighter | Sharp, fruity, astringent | Cakes & biscuits reacting with baking soda |
| Alkalized | 6.8–7.8 (ultra-black to 8.2) | Velvety; red-brown to black | Chocolate, coating creams, ice cream, desserts |
Fat engineering: CBS, CBR and CBE
Cocoa butter melts cleanly at 34–35°C, but global price, volatility and tempering needs push plants toward substitutes.
- CBS (Cocoa Butter Substitutes): lauric palm-kernel (PKO) based; steep SFC curve; no tempering — cooling tunnel sets crystal form. Incompatible with >5% cocoa butter — eutectic softening and fat bloom risk.
- CBR (Cocoa Butter Replacers): non-lauric hydrogenated soy/palm; tolerates ~20% cocoa butter; greasier mouthfeel than CBS.
- CBE (Cocoa Butter Equivalents): matched to POP/POS/SOS triglycerides; 100% mixable with cocoa butter; needs tempering; premium chocolate use.
Flour liberalisation, sugar and price elasticity
Ending preferential FX and freeing industrial flour prices multiplied flour costs; flour is 40–60% of cereal formulas, so COGS jumped. Exchange-traded sugar, FX swings and cane/beet seasonality, plus BOPP/OPP film inflation, activated demand elasticity. Plants turned to shrinkflation and down-trading to protect cash flow.
3. Competitive benchmark of leading holdings
The market is a balanced oligopoly: advantage rests on product quality, value-chain strategy, channel control and line technology.
| Group | Portfolio & segment | Distribution | Differentiation | Est. share |
|---|---|---|---|---|
| Shirin Asal | 1,000+ SKUs; chocolate, biscuit, wafer, cake, toffee, jelly | National van sales + own stores | Full vertical integration (cocoa, print, sugarcane) | 20–25% industrial confectionery |
| Farmand (Parand) | Premium tablets, breakfast cream, jelly powders, caramel, desserts | National wholesale; modern hyper/super focus | Cream rheology; conching & micron milling | 15–18% tablets & breakfast cream |
| Dadash Baradar (Aidin) | Filled toffee, caramel, hard candy, gift chocolate, biscuit | Provincial agents + exclusive stores | Sucrose crystallisation know-how; DE/CH lines | 15–20% toffee & packed chocolate |
| Minoo | Sagheh Talaei, petit beurre, crackers, puffs, layered cake | Ghasem Iran (90k+ outlets) | High-speed cereal baking; nostalgic taste | 25–30% base biscuits & crackers |
| Vitana | Madar kids biscuit, health, digestive, wafers, tarts | Vitana distribution + modern shelf | Caspian megafactory; automated batching | 40%+ kids (Madar) biscuit |
Two winning paths dominate: vertical integration from farm/bean to retail (Shirin Asal) and specialist differentiation in high-value formulas (Farmand in breakfast cream; Minoo in base biscuits).
4. Shelf strategy and retail channels
Brand battles happen within tens of centimetres of shopper eye-line. Distribution has shifted from traditional van sales toward omnichannel, moving power from manufacturers to shelf managers.
- Listing fees: heavy charges per new SKU; a barrier for smaller plants.
- Endcaps: aisle-end space auctioned for Nowruz and Yalda; fuels impulse buying.
- Eye-level planograms: 130–160 cm height; permanent merchandisers defend golden shelves.
Single-brand proprietary stores
Shirin Asal’s (and partly Aidin’s) franchise networks are forward integration: daily cash instead of 60–120-day cheques, cutting 15–25% wholesale margin, a live NPD test market and stronger luxury brand equity.
5. R&D, health focus and line technology
The paradigm is shifting from refined-carb calorie bombs to functional snacks: 60–96% dark chocolate, protein bars at 20–35% WPC/soy isolate, and sucrose replacement with isomalt plus stevia.
- Continuous conching: batch cycles of 24–48 hours cut to under 4 hours; better texture uniformity and energy use.
- Automatic tempering: Form V (beta) nuclei; cool near 27°C and reheat near 31°C for gloss and bloom control.
- Cold-seal flo-pack: heat-free sealing above 800 pcs/min protects cocoa coatings.
6. FAQ for commercial and investment teams
What share of cost do CBS and cocoa powder take?
In Iranian moulding compound, fat is typically 30–35% by weight and 40–50% of BOM cost. Cocoa powder is 8–15% by weight and 20–28% by value; the rest is sugar, milk powder, whey and lecithin (<0.4%).
Why do Tabriz brands lead in CIS and Iraq?
Transit proximity and lower heat damage; linguistic and taste affinity; flexible custom production; and rial–dinar settlement networks in free zones that blunt formal banking sanctions.
Moulding vs enrobing CBS — what differs?
Moulding: higher SFC at 20–25°C for snap and mould release contraction. Enrobing: lower solids and melt viscosity for thin even coats; post-cool flexibility to avoid cracking and flaking.
Barriers to luxury hardbox export to the Gulf?
Limited online-logger cold logistics; print/food-grade board quality gaps (much board is imported); Brand Equity lag versus Swiss/Belgian/Lebanese labels; and Halal/GSO rules including trans-fat caps.
7. Strategic outlook and Iranco’s role
Under input inflation and weaker middle-class purchasing power, pure scale-and-cheap pricing loses edge. Decade winners will reverse-engineer ingredient cost, raise oven/line energy productivity and pair advanced processing with healthier single-serve packs.
- Ingredients: natural/alkalized cocoa, moulding & enrobing CBS with stable SFC, specialty flour, confectionery sugar, isomalt and stevia.
- Machinery: continuous conching, automatic tempering, extrusion and cold-seal flo-pack.
- B2B networking: pooled orders, lower trade costs and export channels to the Middle East, Gulf and Central Asia.
Procurement, R&D and founders can use the Iranco commercial portal to tighten sourcing and lift regional share.
Featured Products
Related Articles